On April 30, 2026, ENTSO-E — the body that coordinates Europe's transmission system operators — published a warning that reframed a crisis most analysts were already tracking. The concern was no longer that data centers couldn't get power. The new concern was that data centers might consume so much of Europe's available generation headroom that grid operators would be forced to curtail renewable energy penetration across the continent.²⁷
That shift in framing captures how far this story has moved. We passed "European data centers face a grid problem" roughly two years ago. We are now at "European data centers have built workarounds so substantial that the workarounds themselves are reshaping the grid."
The numbers behind the original crisis are stark. FLAP-D — the Frankfurt, London, Amsterdam, Paris, and Dublin cluster that accounts for the majority of European data center capacity — runs grid connection queues averaging 7 to 10 years against a data center construction window of 18 to 24 months.¹ Ireland has €5.8 billion in stranded data center investment: fully permitted projects on purchased land that cannot reach commercial operation because the grid cannot connect them.⁶ The Netherlands enacted a national decree in January 2024 prohibiting hyperscale data centers across the entire country except two remote northern municipalities.³² The UK's contracted demand queue tripled from 41 gigawatts (GW) to 125 GW in seven months before emergency reform.³¹
In February 2026, AWS's head of energy markets and regulation for EMEA went on record: "There's a misalignment. We want to expand and grow within two years. These delays are challenging our growth aspirations."⁸ The world's largest cloud operator had committed €15.7 billion to Aragon, Spain — a secondary market selected precisely because it had available grid capacity. The FLAP-D queue was not an acceptable timeline.
European operators did not wait for policy reform. They engineered around the constraint. They did not do it the same way. They fragmented into three structurally distinct deployment patterns — each defined by which regulator's permit authority it triggers and bypasses, each executing in a different geographic zone, each creating a different competitive moat.
Understanding those three patterns is the analytical work this article does. The grid crisis is context. The response patterns are the analysis.
The Framework: Three Patterns, Three Regulatory Wedges
The European grid constraint problem has a common cause — infrastructure that cannot absorb the pace of AI-driven demand growth — but it has produced three structurally different operator responses. Each response exploits a gap between the regulator whose authority it triggers and the regulator whose authority it bypasses.
Pattern 1: Behind-the-Meter (BTM) Combustion. Burn fuel on-site to generate electricity. Bypasses the grid connection queue because no new grid capacity is needed for the behind-the-meter portion. Triggers air permitting requirements, EU Emissions Trading System (ETS) carbon pricing on combustion emissions, and member-state environmental frameworks. Dominant today in Ireland. Emerging in Germany via utility partnerships that supplement existing grid connections.
Pattern 2: Co-located Renewable Self-Consumption. Site the data center adjacent to dedicated wind, solar, hydropower, or biogas generation. Structure supply under member-state self-consumption frameworks. Bypasses both air permitting and the grid connection queue for the renewable portion. Falls under renewable energy policy rather than fossil generation policy. Dominant in Iberia and the Nordics, where geography permits hyperscale co-location at renewable sites.
Pattern 3: Data Center as Grid Asset. Stay grid-connected but use the facility's uninterruptible power supply (UPS) battery fleet to provide ancillary services — fast frequency response, voltage support, capacity — to the transmission system operator (TSO) under the TSO's grid services market. Triggers neither air permitting nor new generation connections. Transforms the data center from net load problem to net grid contributor. Operational at scale in Ireland. Emerging in the UK.
These patterns are not alternatives that operators choose between on preference. They are products of the regulatory environment that a given geography offers. An operator building in Aragon, Spain cannot choose Pattern 1 without the air permits that Aragon's planning regime would grant. An operator building in Dublin cannot deploy Pattern 2 at hyperscale without geographic access to co-located renewable generation. The permit determines the pattern. The geography determines the permit.
The three patterns are not converging. They are hardening as geographic competitive positions, locking capital into specific architectures faster than any European-level policy reform can respond.
The Scale of the Bet
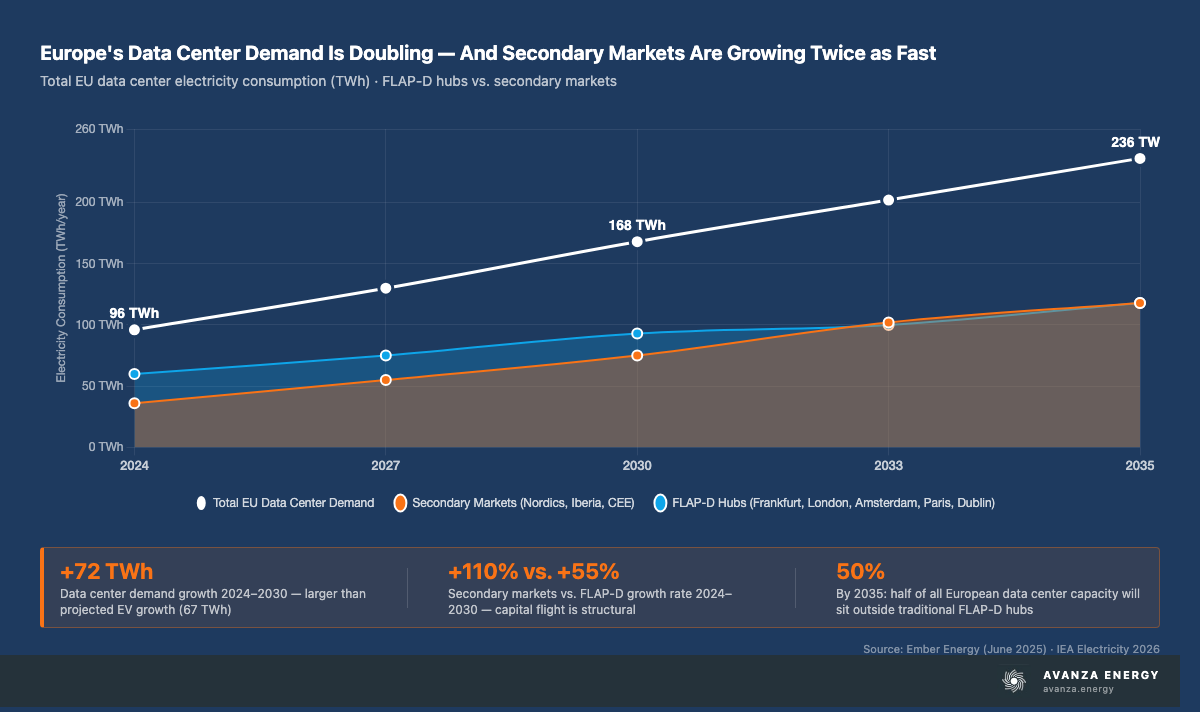
Before examining each pattern, the market context establishes what is at stake. European data centers consumed approximately 96 terawatt-hours (TWh) of electricity in 2024 — about 3% of EU electricity demand.¹⁸ Ember Energy projects this rising to 168 TWh by 2030, a 75% increase in six years.³ Ember Energy's June 2025 analysis extends the trajectory to 150% growth by 2035, reaching 5.7% of total EU electricity consumption.³ For context: data center demand growth between 2024 and 2030 (72 TWh additional) exceeds the projected growth from electric vehicles (67 TWh).³
The European Data Centre Association (EUDCA) has quantified the investment required to meet this demand: €176 billion cumulatively from 2026 through 2031, running approximately €25–26 billion per year for large AI-dedicated scale colocation facilities alone.² The compound annual growth rate (CAGR) for European IT power demand through 2031 sits at 17%.² Grid readiness — not capital availability — is the binding constraint.
The capital is not staying in FLAP-D to wait for the grid. It is redirecting to secondary markets where Pattern 2 executes at hyperscale. Ember Energy projects secondary European markets — Nordics, Iberia, Central and Eastern Europe — will grow 110% between 2024 and 2030 versus 55% for the traditional hubs.³ By 2035, half of European data center capacity will sit outside those hubs.³ Spain absorbed AWS's €15.7 billion Aragon commitment plus Microsoft's $7.16 billion Aragon investment and $2.1 billion Madrid commitment.¹⁰ The Nordics attracted $15 billion in hyperscaler commitments in 2025 alone — Microsoft, CoreWeave, and Brookfield — anchored by Stargate Norway, the OpenAI + Nscale + Aker partnership targeting 230 megawatts (MW) on 100% Norwegian hydropower.¹²
This is not geographic diversification. It is capital flight to places where one of the three patterns can execute.
Pattern 1: The Irish BTM Buildout
Ireland's grid constraint was not abstract for operators. The Commission for Regulation of Utilities (CRU) imposed a de facto moratorium on new data center connections to Dublin's grid beginning in 2021, triggered by data centers reaching 22% of Ireland's metered electricity demand — a share projected to reach 30% by 2030.⁶ CRU's December 2025 decision formally ended the moratorium but replaced it with a requirement that every new connection above 10 megavolt-amperes (MVA) must provide matching dispatchable generation or storage — on-site or proximate — that participates in the Irish Single Electricity Market (SEM).⁶, ⁷ The moratorium became a mandate. The mandate is Pattern 1.
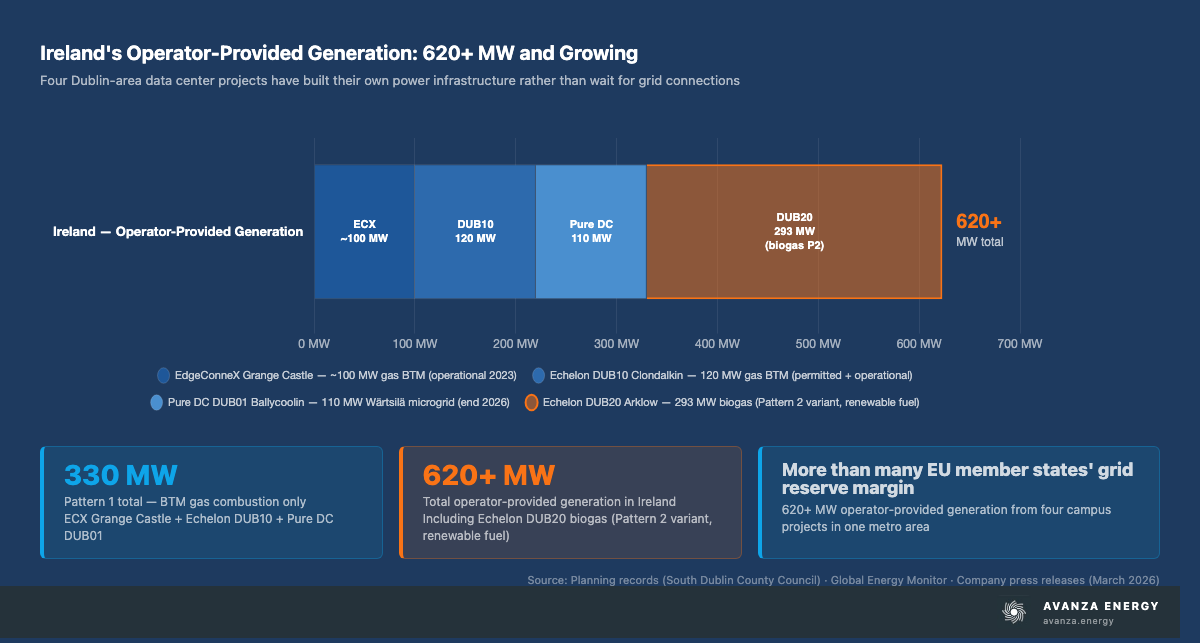
Three operators are executing this pattern in Ireland today, collectively deploying over 600 MW of operator-provided generation:
EdgeConneX Grange Castle (Lucan, County Dublin) — approximately 100 MW gas generation, operational 2023. South Dublin County Council approved three gas-powered generation plants in 2022, with 20 to 21 generator units per plant per planning records. The EdgeConneX Dublin data sheet records 170+ MW of power banked across the campus, supporting two existing and up to five planned data centers. A November 2024 investigation documented 28 emergency generators that have emitted approximately 130,000 tonnes of CO₂ since 2017. Gas Networks Ireland's "Gas to Grange" infrastructure project supplies the fuel. EdgeConneX secured these permits before Irish regulatory tightening. Based on the planning record, the site has not subsequently obtained permission for an additional data center building that would put matched IT load at the same scale as the gas generation — the power infrastructure is substantially in place, but the proportional data center capacity is not fully built out. An Coimisiún Pleanála's August 2025 approval for future generators at the site imposed a condition requiring those generators to run on renewable fuel — signaling that the air permit pathway used in 2022 is closing for future natural gas.
Pure DC Dublin (DUB01, Ballycoolin) — 110 MW Wärtsilä microgrid, announced March 2026. Pure Data Centres Group partnered with AVK-SEG on a €1 billion project building three energy centres of up to 30 MW each, plus 20 MW of battery energy storage.⁴ The system operates in full island mode — it is the primary power source for the campus, not a backup layer. Primary fuel is natural gas; hydrotreated vegetable oil (HVO) provides seamless switching backup; biomethane has been trialed; the system is hydrogen-blend ready with minor modifications. Energy Centres 1 and 2 are operational by end of 2026; EC3 follows.⁴
Pure DC's marketing describes this as "Europe's first microgrid data center." The framing is accurate in one specific sense: it is the first project explicitly branded a microgrid at this scale, and the first designed from inception for full grid independence as the primary operating mode. EdgeConneX Grange Castle and Echelon DUB10 predate it for primary on-site gas generation in Ireland. The "microgrid" term is marketing differentiation, not architectural novelty. The practical consequence of this mislabeling: the actual volume of Pattern 1 deployment in Ireland is substantially larger than the headlines suggest, because ECX has been executing this architecture since 2023 without the microgrid label.
Echelon DUB10 (Clondalkin, Dublin) — 120 MW on-site energy center. Echelon Data Centres' Clondalkin facility includes a 110 kV grid substation and an on-site energy center with planning permission for 100 MVA of gas-fired generation. Global Energy Monitor's power station database records the capacity at 120 MW. Echelon raised €1.7 billion from Morgan Stanley in 2025 to fund Irish expansion, with DUB10 and DUB20 as primary targets.
The regulatory wedge for all three is identical: air permits granted before or during Irish tightening, EU ETS exposure on combustion, and a CRU connection framework that codifies on-site generation as the only viable path. What differentiates Pattern 1 from the alternatives is that it executes immediately wherever air permits are available — but faces a deteriorating carbon economics trajectory as EU ETS prices rise toward €100 per tonne of CO₂ by 2027 and analysts forecast €126 per tonne by 2030.³⁴